

Waiting for Lower Interest Rates Could Cost More Later
If you are thinking about buying a house in metro Atlanta, you have probably heard the advice: “Just wait until interest rates come down.”
It sounds like common sense. High rates make monthly payments steeper, so staying on the sidelines until mortgage rates dip seems like the cautious, financially responsible move.
Here is the catch: Interest rates are unpredictable, but home values in strong markets tend to move in one direction—up.
When you wait for rates to fall, you aren’t waiting in a vacuum. The house you are eyeing today won’t be sitting at the same price next year. While you wait on the sidelines, home prices continue to appreciate, which can erase any savings a lower interest rate might offer.
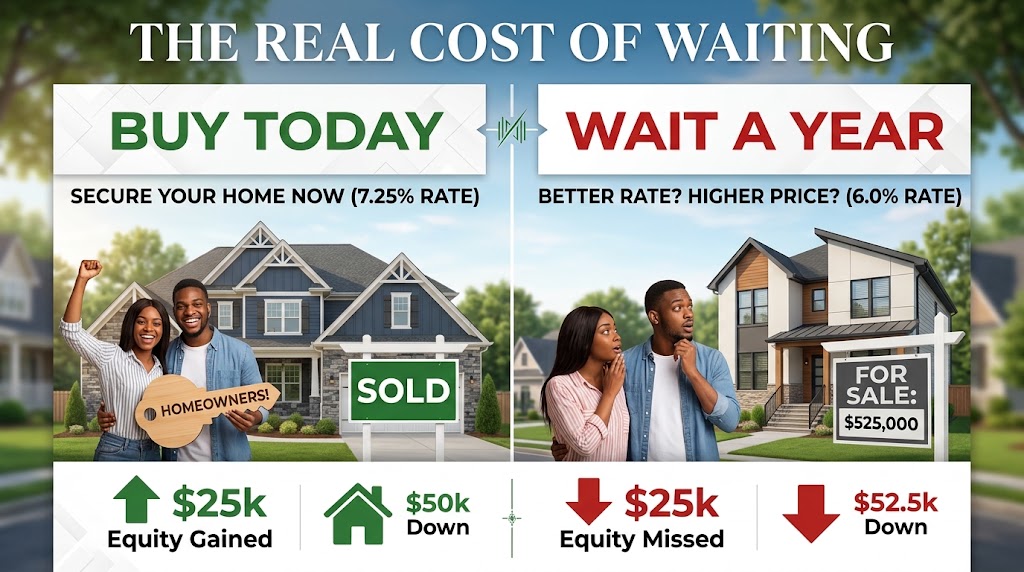
The Atlanta Math: Buy Today vs. Wait a Year
Let’s ground this in a real-world scenario. Say you are shopping for a $500,000 home in metro Atlanta today. Here is how waiting one year for a lower rate actually plays out when you put down 10%.
Scenario 1: Buy Today (2026)
- Purchase Price: $500,000
- Down Payment (10%): $50,000
- Loan Amount: $450,000
- Interest Rate: ~7.25%
- Monthly Principal & Interest: $3,069
Scenario 2: Wait 1 Year for a 6.0% Rate
Assuming a standard 5% local home appreciation rate over the next 12 months:
- New Purchase Price: $525,000
- Down Payment (10%): $52,500 (Requires $2,500 more cash upfront)
- Loan Amount: $472,500
- Interest Rate: 6.00%
- Monthly Principal & Interest: $2,833
What Waiting Really Costs You
At first glance, Scenario 2 looks tempting. Saving $236 a month on principal and interest sounds like a win. But look closer at what sitting on the sidelines actually costs you:
- $25,000 in Missed Equity: By waiting 12 months, you hand $25,000 in wealth creation to the seller instead of building it in your own portfolio.
- $2,500 Higher Down Payment: You have to come to the closing table with more cash out of pocket just to meet the 10% mark on the higher purchase price.
- No Rate Guarantee: There is no promise that mortgage rates will actually hit 6.0% in 12 months. If they hover around current levels, you end up paying a higher rate and a higher price.
The Play: “Marry the House, Date the Rate”
The biggest advantage of buying today isn’t just locking in current home prices—it’s flexibility.
When you buy now, your home’s purchase price is locked forever. If interest rates drop down the road, you can simply refinance your mortgage to lock in that lower monthly payment, all while keeping the equity you gained while sitting in the home.
If you wait for rates to drop, so does everyone else on the sidelines. That surge in buyer demand usually sparks bidding wars, pushing prices up even faster.
Ready to Explore Your Options?
Every buyer’s financial situation is unique, and timing the market is never as powerful as time in the market.
If you want to run the exact numbers for your budget, preferred metro Atlanta neighborhoods, or down payment scenario, let’s connect. No pressure—just clear facts to help you make the smartest financial decision for your future.